Private sector credit growth has accelerated sharply to 35.5%, as declining lending rates, improved bank balance sheets and stronger demand for financing point to a significant recovery in credit flowing to businesses and households.
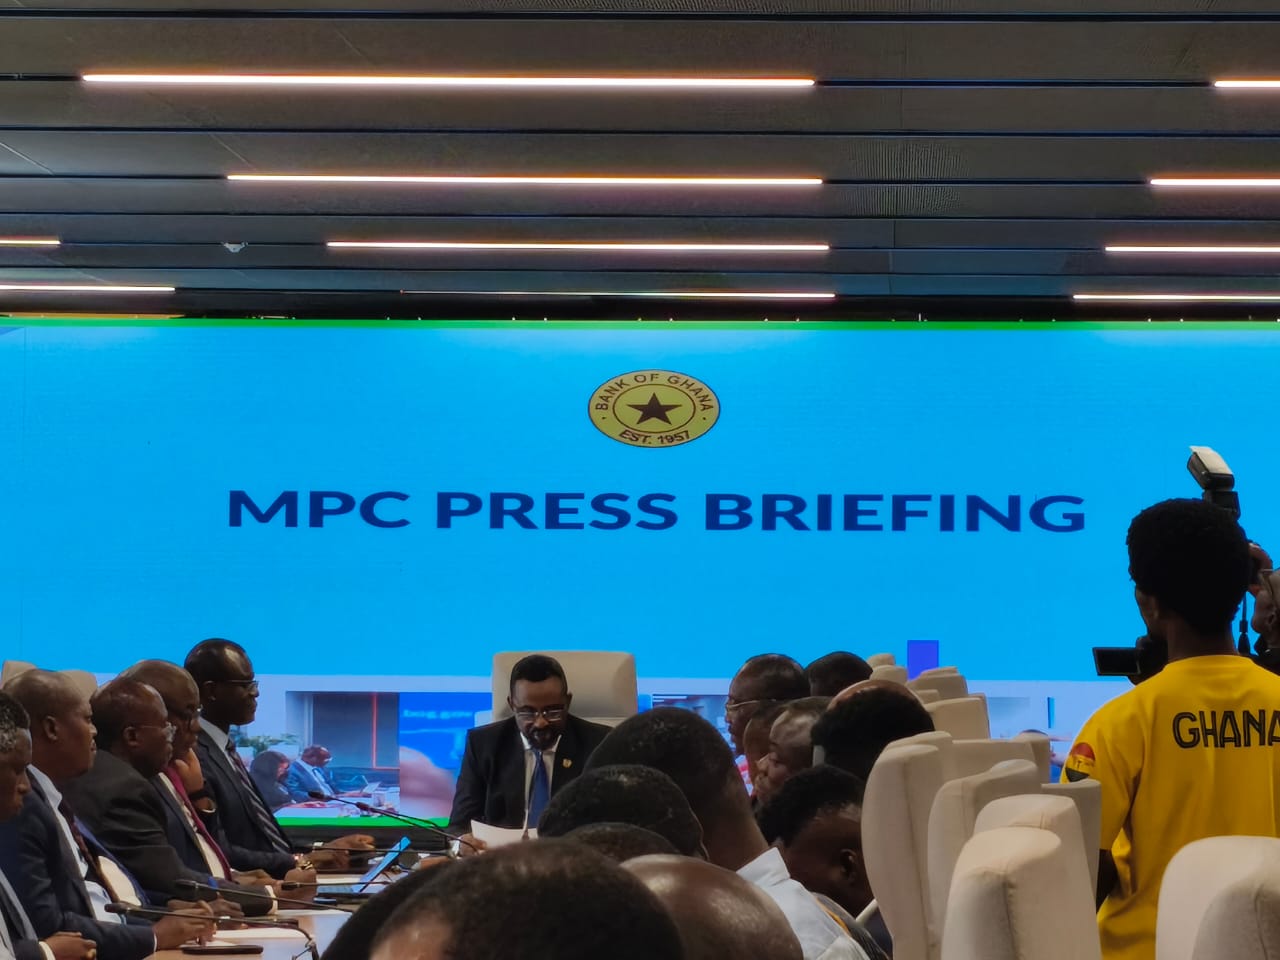
Presenting the latest assessment of Ghana’s financial and monetary conditions on Thursday, Bank of Ghana Governor Dr Johnson Pandit Asiama disclosed that private sector credit growth rose from 13.3% in August 2025 to 35.5% in August 2026.
In real terms, which accounts for the effect of inflation, private sector credit expanded by 29%, compared with just 1.7% over the same period last year.
The sharp increase comes alongside a substantial decline in the average lending rate charged by banks.
The banking sector’s average lending rate dropped to 15.9% in August 2026 from 24.2% a year earlier, representing an 8.3 percentage-point decline.
Rates on short-term government securities have also fallen considerably.
The 91-day Treasury bill rate declined to 5.4% from 10.3% during the corresponding period of 2025.
According to Dr Asiama, the combination of lower interest rates, an easing of banks’ credit stance and increased demand for loans contributed to the acceleration in credit growth.
The development was also reflected in broader measures of economic activity.
The Bank’s updated Composite Index of Economic Activity (CIEA) expanded by 14.9% year-on-year in July 2026, substantially higher than the 6.1% growth recorded in July 2025.
Private sector credit, international trade and consumption of goods and services were among the major contributors to the improvement.
Consumer and business confidence surveys conducted in August also showed positive sentiment, which the central bank attributed to the relatively stable macroeconomic environment and optimism about the country’s growth prospects.
The improvement in credit conditions comes as the banking industry continues to strengthen its financial position.
Total banking-sector assets increased by 20.5% year-on-year to GH¢500.2 billion in August, supported by strong deposit mobilisation and growth in other sources of funding.
The industry’s Capital Adequacy Ratio increased to 19.1% from 18.3% a year earlier, indicating a stronger capital position across the sector.
Asset quality also showed significant improvement.
The ratio of non-performing loans fell to 15.7% in August 2026 from 20.8% in August 2025, alongside the strong rebound in credit.
The Governor described the banking sector as solvent, profitable and liquid, with improving asset quality.
Money circulating through the financial system has also expanded.
Reserve money grew by 29.7% year-on-year in August, compared with 4.5% in August 2025, largely reflecting growth in net domestic assets following changes to reserve requirements.
Broad money supply increased by 20.4%, compared with 16.6% a year earlier.
The credit rebound coincides with continued expansion in the wider economy, although the pace of GDP growth moderated compared with last year.
Real GDP expanded by 6% in the second quarter, while non-oil GDP grew by 5.4%, compared with 8.5% during the same quarter of 2025.
The latest figures suggest that the significant reduction in market interest rates is increasingly transmitting into bank lending, with substantially more credit reaching the private sector than a year ago.